Fixed assets
The Fixed assets (ОЗ і НМА) section holds the accounting of fixed assets and intangible assets. It is shown when Fixed and intangible assets (Основні засоби і НМА) is enabled in Home → Functionality.
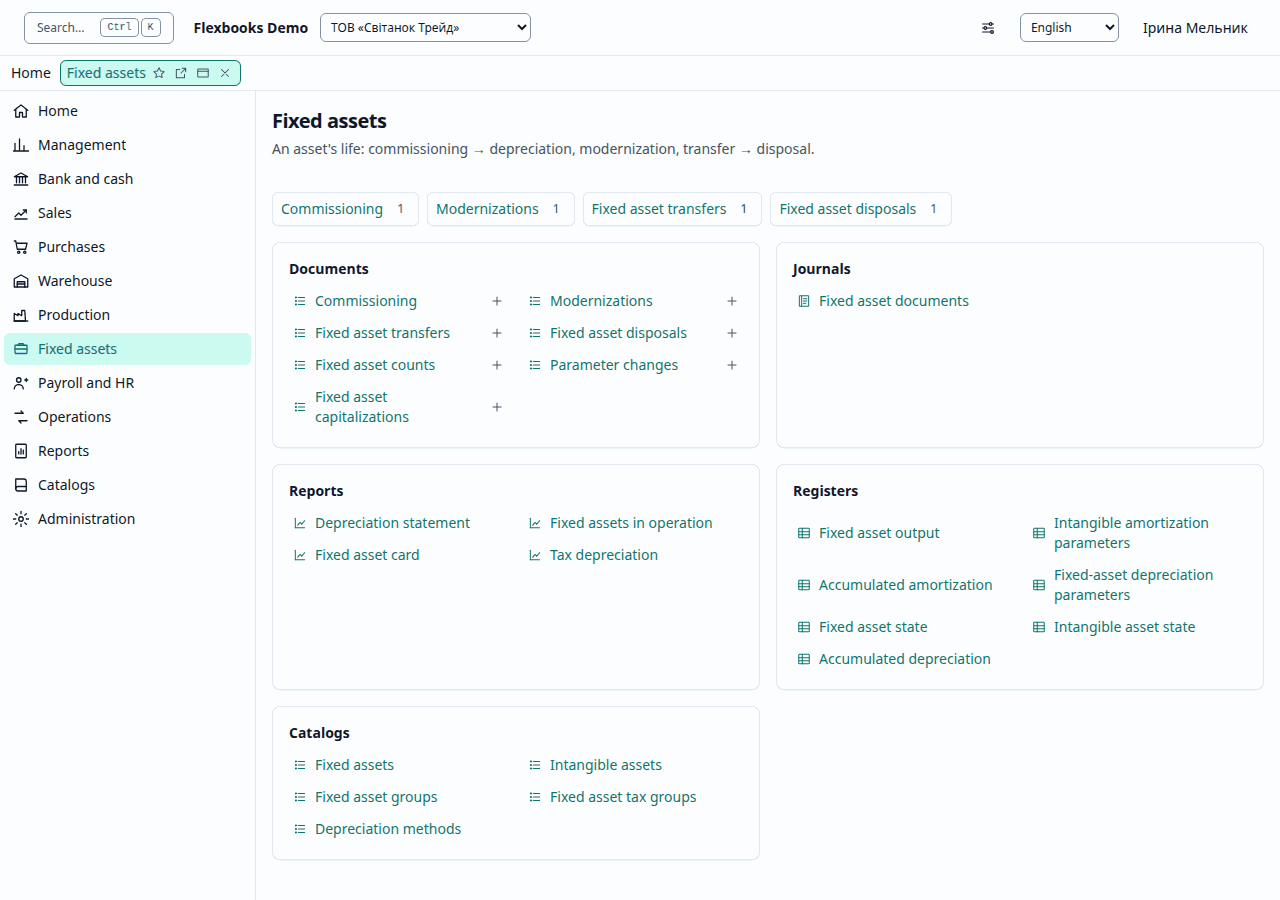
These groups are in the functions panel at the side once you open any list of the section; the section's own page, pictured above, gathers the same links into cards by kind: documents, journals, reports.
| Group | What it contains |
|---|---|
| Important | Fixed asset documents, Fixed assets, Intangible assets |
| More in this section | Commissionings, Modernizations, Fixed asset transfers, Fixed asset disposals, Fixed asset inventories, Parameter changes, Fixed asset capitalizations, Fixed-asset output |
| See also | Fixed-asset groups, Fixed-asset tax groups, Depreciation methods, Fixed-asset depreciation parameters, Fixed-asset state, Intangible asset state, Accumulated depreciation |
| Create | Fixed asset commissioning, Fixed asset modernization, Fixed asset transfer, Fixed asset disposal, Fixed asset count, Depreciation parameter change, Fixed asset surplus capitalization |
| Reports | Depreciation statement, Fixed assets in operation, Fixed asset card, Tax depreciation |
Receipt and commissioning
Equipment arrives with a Receipt of goods and services (Надходження товарів і послуг) document to capital investments (Dr 1521 Cr 631, with the fixed asset and quantity). Fixed asset commissioning (Введення в експлуатацію ОЗ) is created based on a posted receipt, moves the cost from 1521 to the fixed asset account (for example, 104) and records the depreciation parameters and the fixed asset state from the document date. A useful life and method not given on the line are taken from the fixed asset group. The document is printed in form ОЗ-1. A fixed asset already in operation cannot be commissioned a second time.
Depreciation
Depreciation is accrued by the monthly regulated operation Depreciation of fixed and intangible assets (Нарахування амортизації ОЗ і НМА) — the first of the month-end close operations (see Operations), starting from the month after commissioning. Methods:
- straight-line (for example, 12 000 over 12 months — Dr 92 Cr 131, 1 000 a month from the next month);
- reducing balance, accelerated reducing balance, sum of years;
- units of production — by the month's output from the Fixed-asset output (Виробіток ОЗ) register.
The expenses of production fixed assets go to 23, of general production ones to 91, with the division. Tax depreciation uses the minimum useful life of the tax group. An intangible asset: receipt to 154, acceptance to 127, depreciation Dr 92 Cr 133 from the next month.
Changes
- Fixed asset modernization (Модернізація ОЗ) increases the cost (Dr 104 Cr 1522) and depreciates the residual value over the new useful life from the next month.
- Fixed asset transfer (Переміщення ОЗ) moves a fixed asset without entries; from the following months depreciation goes to the new division and account.
- Depreciation parameter change (Зміна параметрів амортизації ОЗ) changes, from the next month, the useful life (rebasing the residual value), the salvage value, the expense account, or turns accrual off ("Accrue depreciation" = no).
Disposal and count
- Fixed asset disposal (Списання ОЗ) accrues the last month's depreciation and writes off the accumulated depreciation and the residual value to 976; it is printed in form ОЗ-3. A sale of a fixed asset fills in the description and VAT rate of the line; a tax invoice is created based on it. A VAT non-payer does not charge VAT on the sale.
- Fixed asset count (Інвентаризація ОЗ) lists the fixed assets on the books; missing ones become a disposal based on it.
- Fixed asset surplus capitalization (Оприбуткування ОЗ) — a surplus at fair value (Dr 104 Cr 746), depreciated from the next month.
Reports
- Depreciation statement (Відомість амортизації ОЗ) — for each fixed asset: opening, accrued, written off, closing; the total accrued equals the credit turnover of 13x.
- Fixed assets in operation (Відомість ОЗ в експлуатації) — fixed assets at a date with cost and accumulated depreciation from the accounting records.
- Fixed asset card (Інвентарна картка ОЗ) — all movements of a fixed asset; printed in form ОЗ-6.
- Tax depreciation (Податкова амортизація) — by tax group, equals the tax register.